Income Protection for Mental Health in New Zealand: What’s Covered?
A mental-health condition can interrupt your income just as seriously as a physical illness. In New Zealand, income protection for mental health may help replace part of your earnings if you’re medically unable to work because of depression, anxiety or another eligible condition. But not…
Income Protection for Sole Traders and Contractors: What to Know
Working for yourself brings freedom, but an illness or injury can interrupt your earnings without warning. Income protection for sole traders and contractors helps replace part of your personal income when a qualifying health condition prevents you from working. Whether you’re a tradie, consultant or…
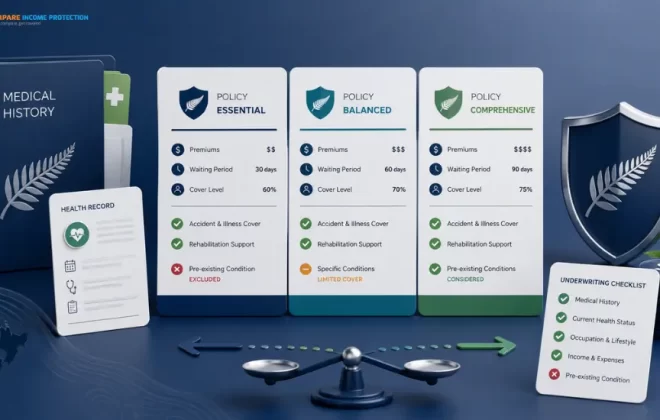

Income Protection Pre Existing Conditions: Can You Still Get Cover?
Having a current or previous medical condition does not automatically rule out income protection. If you are researching income protection pre existing conditions in New Zealand, the key point is that your health history can affect how an application is assessed, but the outcome depends…
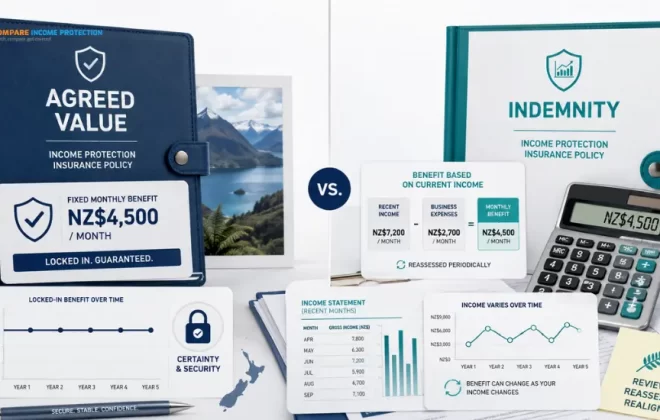

Agreed Value vs Indemnity Income Protection: What’s the Difference?
Comparing agreed value vs indemnity income protection is less about finding one policy type that is universally better and more about understanding how your income would be assessed if you ever needed to claim. The difference can become especially important if your earnings change, you…

Income Protection Insurance Premium: What Affects Your Price
There is no standard income protection insurance premium that suits every New Zealander. Two people earning similar incomes can receive very different pricing depending on their age, occupation, health, smoking status and the way their cover is structured. Even small changes to a waiting period,…
Income Protection Insurance Cost in New Zealand: What Could You Pay?
There is no single price for income protection insurance in New Zealand. Your income protection insurance cost depends on your age, occupation, health, income, and how you structure your policy. A shorter waiting period may allow eligible payments to begin sooner, while a longer benefit…
Income Protection Benefit Period: Which Option Is Right for You?
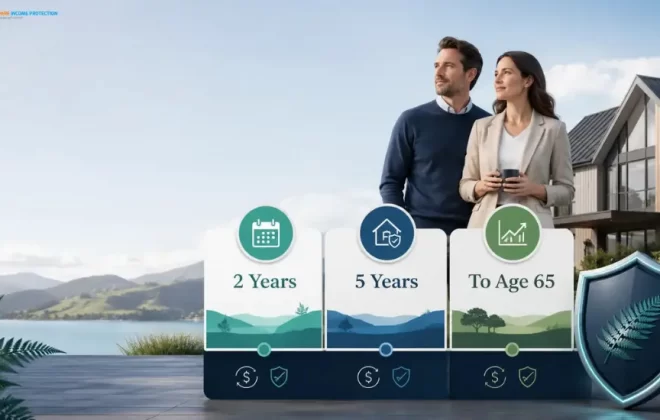
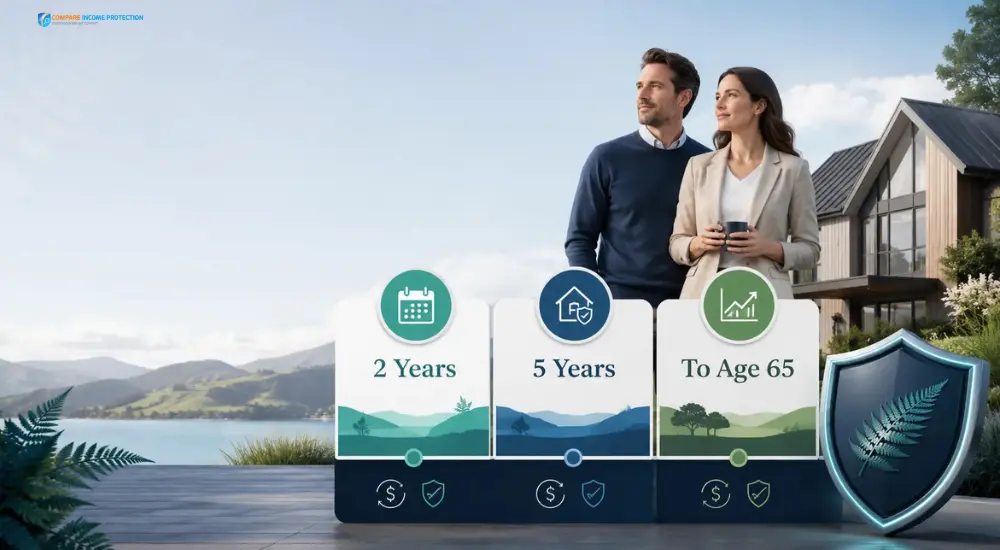
Choosing an income protection benefit period means deciding how long monthly payments could continue if an illness or injury prevents you from working. Depending on the policy, you may be able to choose a fixed period, such as two or five years, or protection that…
Disability Cover vs Illness Cover vs Redundancy Cover in New Zealand
Disability cover vs illness cover vs redundancy cover in New Zealand can sound similar, but they protect very different risks. In most New Zealand search results and insurer content, disability cover usually means TPD cover, illness cover usually means trauma or critical illness cover, and…
Income Protection Insurance vs Life Insurance Policy in New Zealand
TL;DR What they pay and when: A life insurance policy pays a lump sum on death or terminal illness; income protection insurance pays a monthly benefit when you can’t work due to illness or injury. This is the core difference between income…