Switching or Cancelling Income Protection Insurance in New Zealand
Thinking about switching or cancelling income protection insurance in NZ? Before making a decision, it’s worth checking what your existing cover provides and what a replacement might leave out. This guide explains your options, the risks of changing policies, and how to make a confident…
Income Protection for High Income Earners: Compare Costs and Limits
A six-figure salary can make everyday finances more comfortable, but it often supports substantial commitments too. Mortgage repayments, family expenses, investments, and long-term plans may depend on a single regular income. If illness or injury prevents you from working, replacing that income is not always…
Income Protection for Women in New Zealand: Guide to Compare Policies
Income protection for women in New Zealand is about keeping everyday finances manageable if illness or injury stops you from earning. Whether you work full-time, run a business, balance paid work with caring responsibilities or are preparing to return from parental leave, the right policy…
How to Apply for Income Protection in New Zealand and Compare Policies
If you’re wondering how to apply for income protection, start by working out what would happen to your finances if illness or injury stopped you from earning. Comparing policies first can reveal differences in benefits, waiting periods, exclusions and premiums. This guide explains the income…
Income Protection vs TPD: Which Cover Is Right for You in New Zealand?
Comparing income protection vs TPD can feel confusing when both policies promise financial support if you cannot work. The difference is what triggers a claim and how you receive the money. Income protection usually pays a monthly benefit during an eligible period of illness or…
Income Protection CPI Indexation in New Zealand: How It Works
Income protection CPI indexation helps your insured monthly benefit keep up with rising living costs. But it can also affect your premiums, and not every policy increases cover in the same way. Here is what New Zealanders should check when comparing cover. Key Takeaways: Things…
Income Protection for Mental Health in New Zealand: What’s Covered?
A mental-health condition can interrupt your income just as seriously as a physical illness. In New Zealand, income protection for mental health may help replace part of your earnings if you’re medically unable to work because of depression, anxiety or another eligible condition. But not…
Income Protection for Sole Traders and Contractors: What to Know
Working for yourself brings freedom, but an illness or injury can interrupt your earnings without warning. Income protection for sole traders and contractors helps replace part of your personal income when a qualifying health condition prevents you from working. Whether you’re a tradie, consultant or…

Income Protection Pre Existing Conditions: Can You Still Get Cover?
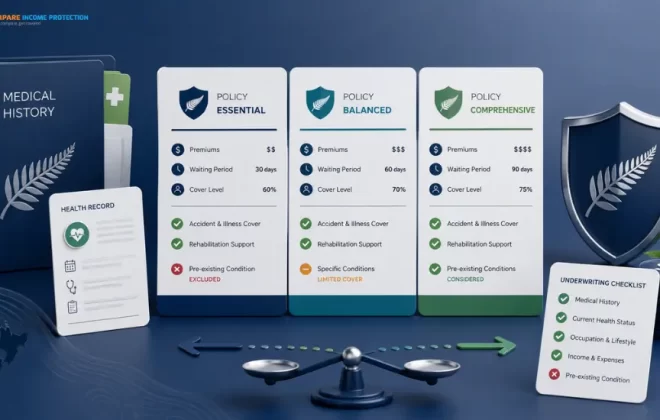
Having a current or previous medical condition does not automatically rule out income protection. If you are researching income protection pre existing conditions in New Zealand, the key point is that your health history can affect how an application is assessed, but the outcome depends…

Agreed Value vs Indemnity Income Protection: What’s the Difference?
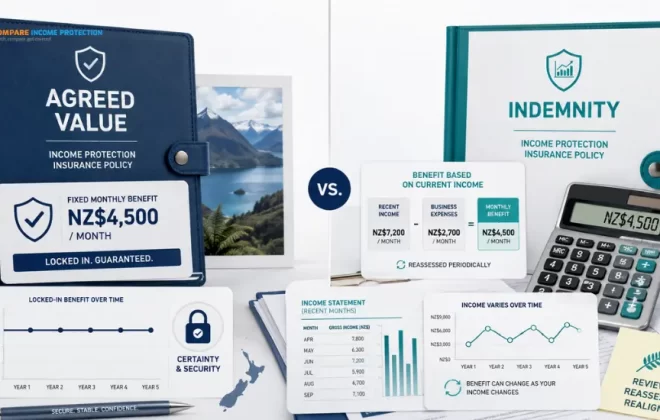
Comparing agreed value vs indemnity income protection is less about finding one policy type that is universally better and more about understanding how your income would be assessed if you ever needed to claim. The difference can become especially important if your earnings change, you…